

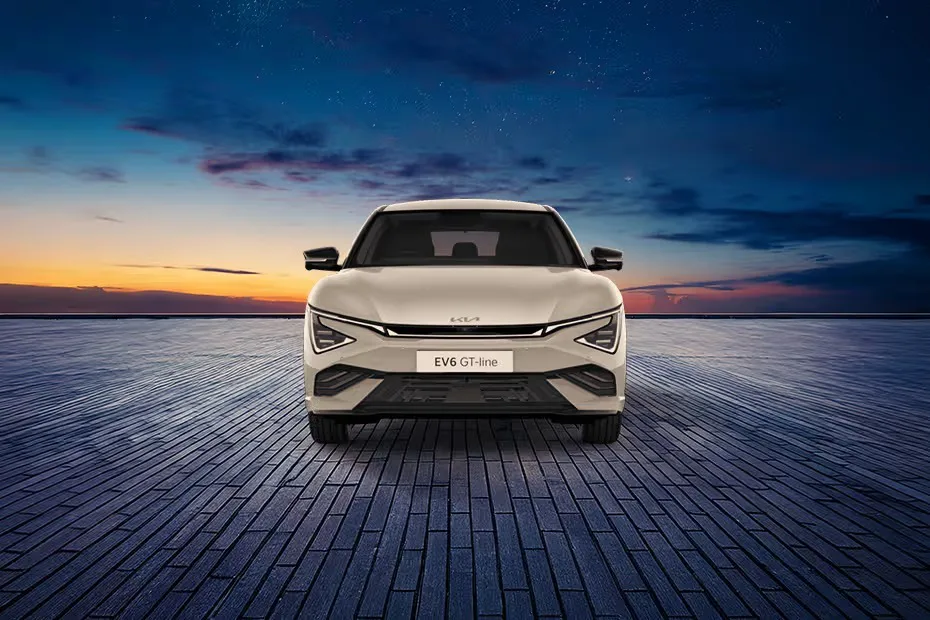
A Kia EV6 EMI Jaipur plan should begin with the exact vehicle quotation and the buyer's real monthly capacity, not with a promotional instalment shown without context. A serious finance comparison connects the current payable amount, a sustainable down payment, lender terms, charging arrangements, ownership costs, and the cash reserve that remains after purchase.
Latest pricing may vary, so request a current quote, confirm current offer, check dealership for current availability, and verify finance terms, stock, waiting periods, delivery timing, and feature availability with Rajesh KIA before booking. Approval, rate, tenure, fees, and the final instalment depend on the financier and applicant profile. Treat every online calculator as a planning tool until the lender provides a written sanction and repayment schedule for the current quotation.
Why Kia EV6 EMI Jaipur Planning Starts With a Current Quote
The amount to finance cannot be judged correctly from an old headline price or another buyer's estimate. Ask Rajesh KIA for a written breakup tied to the exact current EV6 configuration, colour, registration choice, insurance selection, accessories, protection products, and any other item being considered. Separate mandatory components from optional ones so that the loan amount reflects deliberate decisions rather than a combined number that is difficult to audit.
Kia's official website currently provides EV6 product information and an EMI calculator, while established automotive portals publish Jaipur price and finance estimates. These sources are useful for research, but they can use different assumptions for registration, insurance, down payment, rate, or tenure. Use them to prepare questions, then base the actual finance comparison on the current dealership quote and the financier's written terms.
Why Finance Is the Cleanest Current EV6 Buyer-Intent Gap
Current information: prices, offers, finance terms, stock, waiting periods, delivery timing and feature availability can change. Confirm the current details with Rajesh KIA before booking.
The active EV6 landing page already carries price and test-drive articles plus offers, best-variant, and family-versus-city guidance. Repeating them would be stale even though price remains the strongest research signal. Finance is the next practical question at the quotation stage, so this article fills that gap without claiming local EMI popularity.
Step 1: Build the Amount Financed Line by Line
Start with the total on the current written quotation and mark each component. Confirm the vehicle configuration, registration, insurance, optional accessories, protection products, and any offer condition separately. If an exchange adjustment or finance-linked product is discussed, request a clear line for it. The amount financed should be traceable from the quote instead of being inferred from a rounded monthly figure.
Ask for a revised illustration if the quotation changes before invoicing. A colour change, optional product, insurance choice, registration treatment, or revised offer can alter the amount due. The down payment and sanctioned amount should reconcile with the latest documents before disbursement.
Step 2: Choose a Down Payment That Preserves Liquidity
A larger down payment can reduce borrowing, but using every available rupee upfront can weaken the reserve needed for emergencies, home commitments, business working capital, insurance renewal, charger installation, or other planned expenses. The useful down payment is the one that reduces the loan while leaving the household financially resilient after the vehicle is delivered.
Compare three scenarios using the same quotation and lender assumptions: a comfortable contribution, a moderately higher contribution, and the maximum amount that still preserves a sensible cash buffer. Record the resulting loan amount, monthly instalment, total repayment, and liquid funds remaining. Reject any scenario that depends on uncertain income, an unconfirmed asset sale, or emergency savings.
Step 3: Compare Complete Lender Terms, Not One EMI
Request comparable written illustrations for the same loan amount and then vary one factor at a time. For each option, record the rate type, applicable rate, tenure, instalment, total interest, total repayment, processing and documentation fees, taxes on charges, instalment date, and rules for part-payment, prepayment, foreclosure, and late payment. Confirm whether the illustration includes an advance instalment or another upfront payment.
A lower displayed EMI can come from a longer tenure, a larger down payment, or costs placed outside the monthly number. It is not automatically the more comfortable plan. Compare total repayment, the length of the commitment, flexibility to reduce the balance later, and the effect on monthly savings before choosing.
Step 4: Add Charging and Ownership Costs to the Budget
The instalment is only one part of EV6 ownership. Add a realistic monthly or annual allowance for home-charging preparation where required, electricity, public charging, parking, tolls, cleaning, insurance renewal, periodic service, tyres, and unexpected expenses outside routine cover. Do not use a guaranteed saving or fixed future energy cost; create a conservative range based on the routes and charging access you actually expect.
Discuss the intended parking and charging arrangement before finalising the finance plan. A buyer with reliable home charging may budget differently from someone who expects to use public charging frequently. Ask Rajesh KIA to confirm the current charging equipment and installation process applicable to the vehicle, then keep any related cost visible outside the EMI comparison.
Step 5: Match the Finance Plan to Real EV6 Usage
Write down who will drive the vehicle, typical daily distance, regular passenger load, city-to-highway mix, overnight parking, and the longest journeys that matter. These details influence charging planning, insurance needs, and the amount of financial flexibility worth retaining. A premium EV should fit the household's transport pattern as well as its spreadsheet.
Take a representative test drive and confirm the exact current configuration before finance is locked. If the preferred vehicle or feature set changes after the drive, request a fresh quote and repeat the comparison. Financing the wrong configuration efficiently is still the wrong purchase decision.
Step 6: Stress-Test Kia EV6 EMI Jaipur
Test the preferred plan against a difficult month. Ask whether the instalment and normal ownership reserve remain manageable if income is delayed, another loan payment overlaps, travel increases, or a family expense appears. Salaried buyers should include existing commitments and predictable annual goals. Self-employed buyers should compare the EMI with a conservative average month rather than the strongest recent month.
If the plan works only when every assumption is favourable, reduce the amount financed, increase the down payment without weakening reserves, choose a different tenure, revise optional items, or delay the decision. A healthy plan should leave room for savings and unexpected costs instead of consuming the entire monthly surplus.
Step 7: Reconcile the Sanction With the Final Quote
Before signing, verify the applicant name, sanctioned amount, rate type, applicable rate, tenure, instalment, total repayment, fees, optional products, late-payment consequences, and prepayment conditions. Confirm the amount the financier will send to the dealership and the amount the buyer must pay directly. Ask for corrected documents if any figure differs from the latest quotation.
Do not treat verbal approval as final. Finance eligibility and terms can change after document review or when the quotation changes. Keep copies of the quote, sanction letter, repayment schedule, receipts, insurance selection, and final invoice so each payment can be matched to a document.
Practical EV6 Finance Comparison Checklist
- Exact current EV6 configuration, colour, and feature availability.
- Written on-road breakup with mandatory and optional items separated.
- Down payment, amount financed, tenure, instalment, and total repayment.
- Rate type, processing fee, documentation charges, and taxes on charges.
- Part-payment, prepayment, foreclosure, and late-payment conditions.
- Insurance, accessories, protection products, and offer conditions shown separately.
- Home and public charging plan with related costs outside the EMI.
- Monthly and annual ownership reserve after paying the instalment.
- Sanction details reconciled with the current dealership quotation.
Warning Signs That Should Pause the Decision
Pause if the discussion shows only a monthly number, the quotation does not identify the exact current configuration, optional products are bundled without explanation, or total repayment is missing. Also pause if an unverified offer is used to make the plan appear affordable, the down payment consumes emergency savings, or the repayment depends on uncertain future income.
Request clarification in writing. A short review delay is safer than proceeding with an unclear sanction, quote mismatch, or unsupported incentive. If pricing, finance terms, stock, delivery timing, or feature availability changes before invoicing, ask the dealership and financier to refresh the relevant documents.
Frequently Asked Questions About Kia EV6 EMI Jaipur
How should I estimate Kia EV6 EMI Jaipur?
Start with a current written quote, subtract a down payment that preserves a cash reserve, and compare complete lender illustrations across suitable tenures. Treat online calculators as estimates and confirm approval, rate, charges, instalment, and total repayment in the final documents.
Should I choose the lowest monthly instalment?
Not automatically. A lower instalment may result from a longer tenure, a larger upfront contribution, or charges outside the monthly number. Compare total repayment, flexibility, remaining liquidity, and ownership costs before deciding.
What should the written EV6 quotation include?
It should identify the exact current configuration and separate registration, insurance, optional products, applicable offer conditions, and total payable. Ask Rajesh KIA to explain or revise any unclear line before finance is finalised.
Should charging costs be included in the EMI worksheet?
Yes, but keep them as a separate ownership budget rather than hiding them inside the instalment. Use your likely home and public charging pattern, confirm current equipment and installation requirements, and allow a conservative range instead of assuming a fixed future cost.
Can final finance terms differ from an online calculator?
Yes. A calculator is a planning tool. The financier decides eligibility and final terms using the application, documents, credit profile, loan amount, and current policy. Review the written sanction and repayment schedule before treating any estimate as final.
What should I confirm before booking?
Request a current quote, confirm current offer, verify the exact EV6 configuration, and check finance terms, stock, waiting periods, delivery timing, feature availability, charging arrangements, and lender conditions with Rajesh KIA.
Plan Your Kia EV6 EMI Jaipur With Rajesh KIA
Bring your comfortable down-payment range, monthly ceiling, existing commitments, charging plan, and required documents to the discussion. Ask for a current quotation and more than one complete finance illustration, then compare instalment, total repayment, charges, ownership reserve, and remaining liquidity before making the booking decision.
Request a current Kia EV6 EMI Jaipur quote and finance comparison from Rajesh KIA.
Comments (0)
Leave a Comment